Avoid a $15,190 Bill: Skilled Nursing Medicare Coverage, Central Oregon
Medicare Part A covers skilled nursing facility care, but only under strict conditions and only for a limited time. You need a qualifying 3-day inpatient hospital stay, a doctor’s order for daily skilled care, and a Medicare-certified facility. Coverage runs free for days 1 through 20, then requires daily coinsurance for days 21 through 100, after which you pay all costs yourself.
TL;DR:
- Medicare covers skilled nursing facility care only after a qualifying hospital stay of at least three days and within approximately 30 days of discharge.
- Coverage is fully paid for the first 20 days, but from day 21 to 100, patients pay a daily coinsurance of $217 in 2026.
- The benefit period resets after 60 days without inpatient care, meaning a new deductible and potential costs must be met for subsequent stays.
- Observation stays do not count toward the three-day inpatient requirement, which can disqualify patients from SNF benefits.
- Secondary coverage, such as Medigap or Medicaid, can help cover coinsurance costs and custodial care is not covered by Medicare after skilled care ends.
Table of Contents
- What Does Skilled Nursing Medicare Coverage Actually Include?
- What Are the Eligibility Requirements for SNF Coverage?
- How Much Does Skilled Nursing Cost Under Medicare in 2026?
- How Is Coverage Different Under Medicare Advantage?
- What Should You Do Before a Skilled Nursing Stay?
- What Happens if Medicare Denies Coverage or You Run Out of Days?
- How Mountaintop Insurance Helps With Medicare Coverage Questions
- Why the 3-Day Rule Deserves More Attention Than It Gets
- Get a Free Medicare Coverage Review With Mountaintop Insurance
- Sources
- FAQ
What Does Skilled Nursing Medicare Coverage Actually Include?
Part A pays for a defined bundle of services once you qualify: a semi-private room, meals, skilled nursing care, physical and occupational therapy, speech-language pathology, medical social services, and medically necessary drugs, supplies, and equipment used during the stay. Ambulance transport can be covered too, when moving you meets medical necessity rules.
The design is rehabilitative, not residential. Medicare built this benefit for people recovering from a stroke, hip replacement, or serious infection who need daily skilled attention for a stretch of weeks, not a permanent home. That’s the distinction that trips up more families than any other part of this benefit: Medicare Part A does not cover long-term custodial care like help to bath, dressing, or eating unless that help arrives alongside genuine skilled treatment during a short post-hospital window.
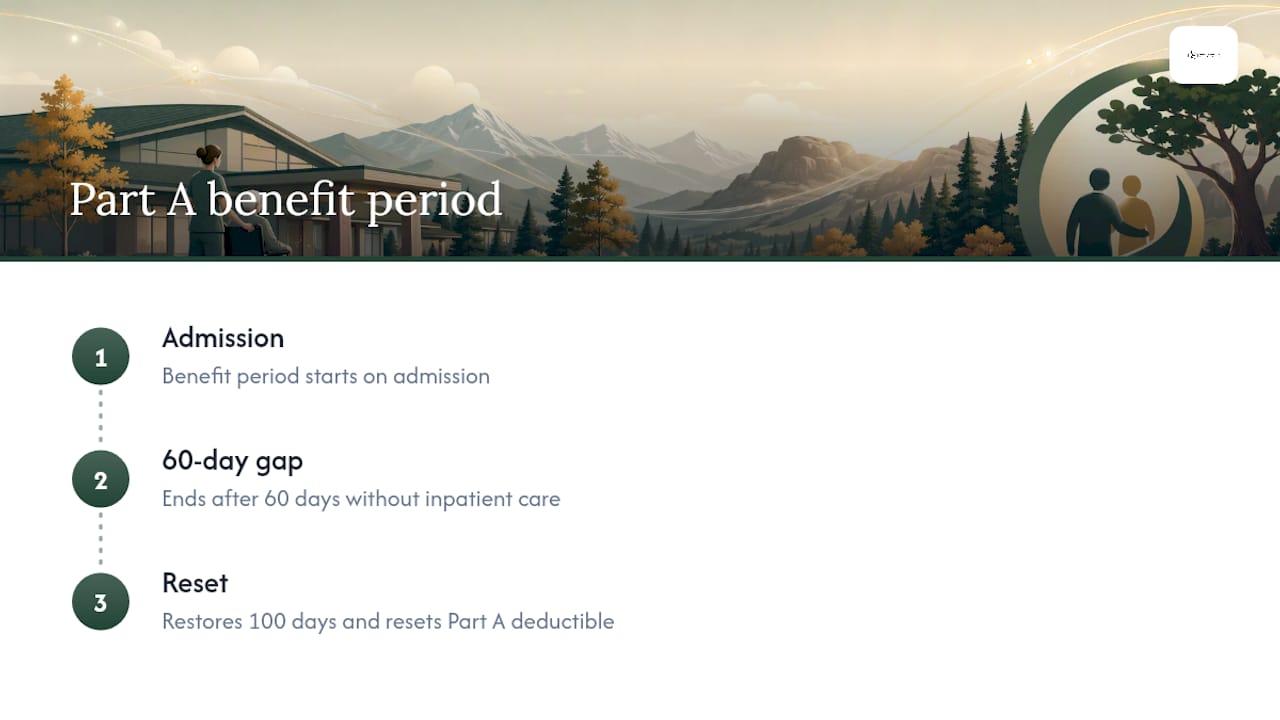
Your coverage clock runs on something called a benefit period, which starts the day you’re admitted as an inpatient and ends after you’ve gone 60 days in a row without inpatient hospital or skilled nursing care. Each benefit period resets your available days back to 100 and resets your Part A deductible, too. That means a second hospitalization later in the year, separated by more than 60 days from the first, can trigger a whole new deductible even within the same calendar year.
What Are the Eligibility Requirements for SNF Coverage?
Four boxes need to be checked before Medicare pays a dime toward skilled nursing facility care:
- You’re enrolled in Part A with unused benefit days remaining in your current benefit period.
- You had a qualifying inpatient hospital stay of at least 3 consecutive days. Time spent under observation status does not count toward this, no matter how many nights you slept in a hospital bed.
- You enter a Medicare-certified SNF within roughly 30 days of hospital discharge, and a doctor certifies you need daily skilled nursing or rehabilitation services.
- You’re actually receiving the skilled care you were admitted for, not just occupying a bed.
There’s one useful exception worth knowing: if you stop needing skilled care and then need it again within 30 days, you often resume the same benefit period without a new qualifying hospital stay. Medicare Advantage enrollees face a different rulebook entirely, covered below.
How Much Does Skilled Nursing Cost Under Medicare in 2026?
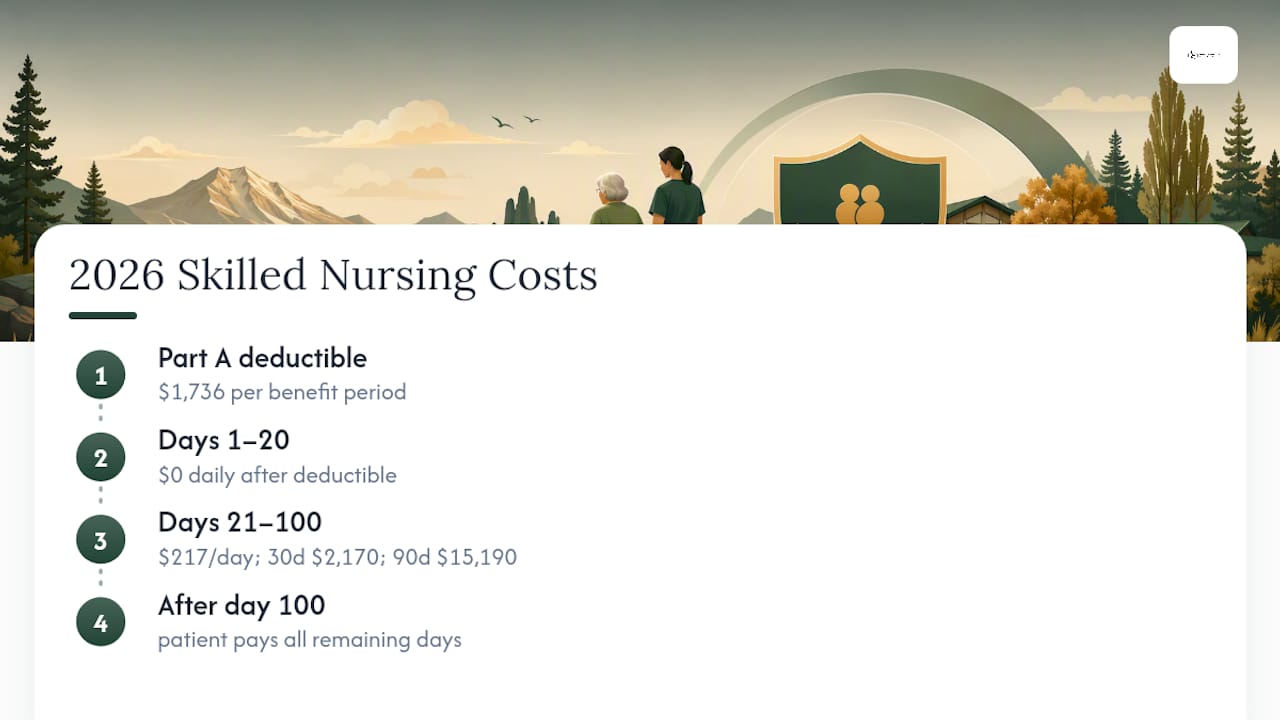
Statistic Callout: As of 2026, the Part A deductible is $1,736 per benefit period. Days 1 through 20 in a skilled nursing facility cost you nothing beyond that deductible. Days 21 through 100 have a set daily coinsurance charge. Past day 100, you’re responsible for the entire bill.
Run the numbers and the stakes get clear fast. A 30-day stay, after the deductible, adds 10 days of coinsurance at $217 apiece, which is $2,170 out of pocket on top of the deductible you likely already paid at the hospital. A 90-day stay pushes that to 70 days of coinsurance, or $15,190, plus the deductible. Stretch past 100 days and every remaining day is entirely yours to cover.
This is exactly where secondary coverage earns its keep. A Medigap plan can pick up that daily coinsurance for days 21 through 100, turning a five-figure worry into a manageable premium. Medicaid can step in for those who qualify financially, and long-term care insurance covers ground Medicare never touches at all, including custodial care after skilled coverage ends.
How Is Coverage Different Under Medicare Advantage?
If you’re enrolled in a Medicare Advantage plan instead of Original Medicare, the rules shift. Your plan may require prior authorization before it approves an SNF stay, and it will likely limit you to facilities inside its network. Some Advantage plans waive the 3-day hospital stay requirement, which sounds like a win, but they usually replace it with their own utilization review and preauthorization steps that can be just as restrictive.
Before any transfer happens, call the plan directly and check the Evidence of Coverage document. Confirm the specific facility participates in the network and find out exactly what preauthorization looks like, because a denied authorization after the fact is far harder to fix than a phone call beforehand.
What Should You Do Before a Skilled Nursing Stay?
Move through this checklist while you’re still at the hospital, not after you arrive at the facility:
- Ask the discharge planner directly whether your hospital stay qualifies as 3 consecutive inpatient days, and get that classification in writing.
- Ask the receiving facility whether it’s Medicare-certified and confirm which specific services it will bill to Part A.
- Call 1-800-MEDICARE with your hospital and SNF dates on hand, along with your Medicare number, to verify benefit days remaining.
- If you’re weighing Medigap or Medicare Advantage implications, that’s the moment to talk to someone who handles this daily.
Pro Tip: Ask the hospital for your inpatient status classification the day you’re admitted, not the day before discharge. Reclassifying an observation stay after the fact is far harder than catching it early.
What Happens if Medicare Denies Coverage or You Run Out of Days?
If a facility believes Medicare won’t cover part of your care, they’re required to give you a Skilled Nursing Facility Advance Beneficiary Notice, known as an SNF ABN, before providing that noncovered service. It tells you what Medicare likely won’t pay for and roughly what it will cost you, so you can decide whether to proceed.
You have the right to appeal both inpatient status determinations and outright coverage denials, and timelines for filing move fast, often within days of receiving a denial notice, so act as soon as you see one. If you exhaust your 100 days or don’t qualify at all, Medicaid or PACE programs may help those who meet income and asset limits, while a Medigap policy can absorb coinsurance for days 21 through 100. Contact your state Medicaid office or a licensed agent for guidance specific to your situation.
How Mountaintop Insurance Helps With Medicare Coverage Questions
Medicare’s SNF rules are consistent nationwide, but how they intersect with your specific plan, your Medigap policy, or your Advantage network is never one-size-fits-all. A local insurance provider specializes in guiding residents through Medicare Parts A, B, C, and D, offering free consultations focused on education rather than sales pressure.
That local, no-pressure approach matters most exactly when a hospital discharge is looming and a family needs clear answers fast, not a pitch. For readers who want to go deeper before that conversation, Some sources publish plain-language breakdowns of the Part A deductible and benefit periods and how Medicare Advantage plans actually operate, which can be helpful to read before consulting with an agent.
Why the 3-Day Rule Deserves More Attention Than It Gets
The single biggest gap between what families expect and what Medicare delivers isn’t the coinsurance schedule. It’s the assumption that any hospital stay counts as inpatient time. Hospitals have leaned harder on observation status over the past decade for billing and utilization reasons that have nothing to do with a patient’s actual medical need, and that shift quietly strips SNF eligibility from people who genuinely needed the hospital.
Most guidance treats the 3-day rule as a footnote. It shouldn’t be. If there’s one thing every caregiver should do differently, it’s asking about inpatient classification on day one of a hospitalization, not day three when it’s too late to fix.
The dollar figures matter too, and $217 a day adds up faster than most people expect over a 90-day recovery. But the coinsurance schedule is at least predictable. The observation status trap is not, and it’s the one place where a five-minute question at admission can save a family thousands of dollars and weeks of appeals. Medigap and Medicaid exist precisely because Medicare was never designed to cover everything, and pretending otherwise sets families up for a bad surprise at the worst possible time.
— Jesse Zimmerman
Get a Free Medicare Coverage Review With Mountaintop Insurance
Some local agents offer straightforward information on Medicare skilled nursing coverage and provide free consultations to review Part A benefits, compare options like Medigap or Medicare Advantage, and explain what to expect if coverage issues arise.
This works best for anyone facing a hospital discharge soon, or for families who just want their coverage reviewed before a crisis forces the question. Consultations are educational, free, and available in person or remotely for Central Oregon residents. Schedule a consultation with Mountaintop Insurance and get your Medicare questions answered by someone who explains options instead of selling them.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Skilled nursing (Original Medicare coverage guidance)
- Skilled Nursing Facility billing reference (CMS MLN)
FAQ
How Long Will Medicare Pay 100% of a Skilled Nursing Facility Stay?
Medicare covers days 1 through 20 with no coinsurance after your Part A deductible is met. Starting day 21, you owe $217 per day in coinsurance through day 100.
What Happens if an Elderly Person Can’t Afford a Nursing Home?
Medicaid can help cover nursing home costs for those who meet income and asset limits, and PACE programs offer another option in some areas. Licensed agents can also review whether a Medigap policy would reduce potential coverage gaps.
How Much Skilled Nursing Will Medicare Pay For?
Original Medicare pays for up to 100 days of skilled nursing facility care per benefit period, provided you meet the 3-day qualifying hospital stay and other eligibility rules. After day 100, you’re responsible for the full cost.
Why Won’t Medicare Pay for Nursing Homes?
Medicare Part A is built for short-term, medically necessary skilled care, not long-term custodial care like help with daily activities. Once your condition no longer requires daily skilled treatment, or once you exhaust your 100 days, Medicare stops paying and you’re responsible for costs unless you have Medicaid, long-term care insurance, or other coverage.
Recommended
Disclaimer: This article is for general educational purposes only and does not constitute personalized advice. Medicare rules and plan details change frequently.
Discuss Your Situation With Us